
General liability insurance for companies
General liability insurance concerns a company's liability for harm caused to other people within the activities and conditions accepted in the policy. It does not insure the company's own buildings or stock. For a business in the Republic of Moldova, assessment starts with its workplaces, operations and the people who could be affected.
This material is for shops, workshops, service providers and other companies interacting with visitors, customers or neighbours. It helps prepare questions without determining liability for an incident or confirming cover for every loss. An actual situation requires examination of the facts, contractual documents and applicable legal framework.
What harm to a third party means
In this discussion, a third party is someone other than the insured, according to policy definitions. A claim may concern damaged property or bodily injury. Identify the claimant, the property's owner and the company operation involved. The relationship between parties should be described rather than assumed.
MOLDCARGO's public page describes property damage and bodily injury within third-party liability. This is a local reference, not confirmation that every person and situation is accepted. Request the definitions in the actual proposal, including the treatment of employees, contractors and people within the same contractual relationship.
Company property insurance has a different subject
If an event affects both company property and a neighbour's belongings, separate those loss categories. Your own furniture, equipment and stock require consideration of property insurance. The neighbour's claim requires clarification of company liability and the protection provided by the relevant policy.
This example organises the questions; it does not promise a claims outcome. Sharing a location or cause does not make two contracts identical. Ask for a comparison that clearly shows each proposal's subject and the issues still requiring confirmation.
Describe all operations that could affect other people
Record ordinary activities, including delivery, installation, maintenance and work on customer premises. A shop selling products does not have exactly the same profile as one also installing equipment. A short description on a receipt or invoice may be insufficient for assessing the operations.
Include seasonal work, new activities and subcontracted services. Identify mobile machinery and work in shared spaces. Do not understate activities simply to obtain a lower price. The proposal should be assessed against real operations and relevant locations, rather than an incomplete commercial label.
Premises, shared areas and work at customer sites
Describe entrances, areas accessible to the public, circulation routes and neighbouring spaces. Record who manages common areas and carries out maintenance. This information assists assessment but does not automatically establish a particular party's fault in an actual situation.
For teams working away from the main premises, explain the operations and their duration. Check whether the proposal accepts them, in which territories and subject to what boundaries. A policy described by a shop address does not itself demonstrate protection for every visit to customers or other sites.
Customers' property in your care needs a separate discussion
A workshop, warehouse or service business may receive property owned by others. Explain what is accepted, where it is kept and the handover records. Distinguish a visitor's belonging near a work area from an item expressly handed to the company for a particular task.
Request clarification of property belonging to others while in custody, use or processing. The term “third party” does not resolve all these situations. Separate boundaries or assessment may be required. Keep records of receipt and condition without collecting unnecessary photographs or personal information.
Delivered products and completed work
Explain whether the risk arises during work on your premises, during installation or after the job is handed over. Identify checking procedures, acceptance records and customer instructions. The timing of a claim and its alleged cause may raise different questions from an incident occurring inside the shop.
Ask whether product liability, completed operations or professional services require separate assessments. Do not assume inclusion from the name “general liability”. For a meaningful comparison, request a written explanation of these boundaries and retain the answers with the proposal.
Do not confuse general liability with other insurance
RCA concerns a separate motor liability framework. Professional liability assesses declared professional services. Employee claims, management claims and cyber incidents may need other checks. Identify the activity and affected person before deciding which contract should be examined.
One policy should not be presented as a solution for every company obligation. For a construction project, for example, compare the customer's requirements with works insurance and the liability under assessment. A list of product names does not establish continuous protection across every activity, period and person involved.
How to compare limits, excesses and premiums
The insurance premium is the amount paid for insurance. Compare the same activities, sites, periods and requested categories of harm. Check the limit for one event and the whole period where the proposal distinguishes them. Explain whether a single operation could affect several people or belongings.
An excess or deductible is the portion of a loss borne by the insured under the contract. Read the exclusions, meaning situations without cover. Request a hypothetical calculation and an explanation of defence costs. Neither a headline limit nor a numerical example confirms compensation for a real event.
Prevention and incident records
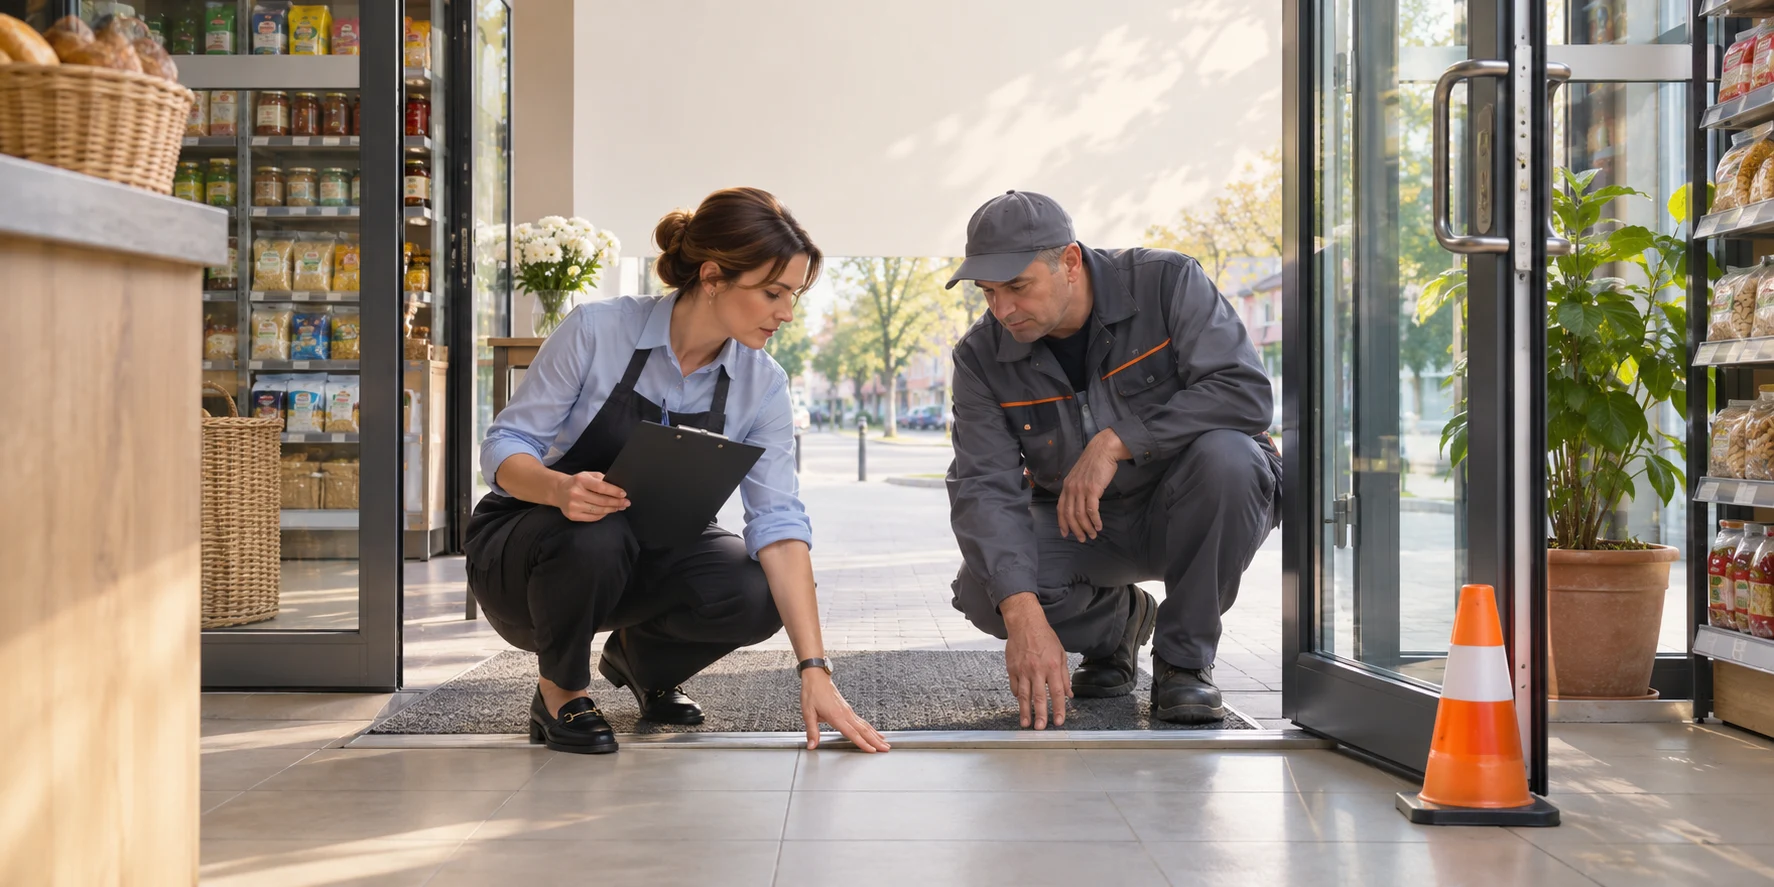
Maintain a clear internal reporting route for defects and observed hazards. Document relevant maintenance and interventions. A damaged mat, leaking installation or blocked entrance is an operational issue for competent people to assess and remedy, not something to leave for a future compensation payment.
These suggestions are not safety certification and do not replace the company's applicable legal or technical requirements. They organise information and identify responsible people. Describe the real situation to the insurer, including known problems, without claims of zero risk or fabricated inspection records.
Clarify the landlord's and tenant's roles
For leased premises, read the provisions on maintenance, installations and public access. Identify work carried out by the owner, tenant or building manager. The label “rented office” does not explain who performed an intervention or who is liable for alleged damage.
Present the operational division to the insurer and ask which risks are assessed and where their contractual boundaries lie. An article does not change the parties' obligations, and building insurance does not automatically protect a tenant's activities. In an incident, liability requires analysis of facts and documents, with legal assistance where necessary.
Update the assessment when the business changes
A new outlet, longer opening hours or an installation service may change the activity description. Assign an internal owner for updates and ask for conditions to be reviewed before the new operation. Avoid automatic renewal from an old file when the company already operates elsewhere or serves different customer groups.
A company file for third-party liability assessment
- Actual activities and secondary services.
- Premises, common areas and operations elsewhere.
- Visitor, customer and partner categories that could be affected.
- Other people's property accepted for storage, repair or processing.
- Subcontracted work and coordination arrangements.
- Delivered products and after-sales operations.
- Known incidents and claims, described factually.
- Requested limits and customer contract requirements.
Initially, organise information by category without named visitor lists or copies of customer documents. Send only necessary information through the agreed channel. This file is an editorial preparation recommendation, not a form confirming acceptance of the risk or an insurance contract.
After an incident: notification and preserving facts
Prioritise people's safety and preventing the situation from worsening, with competent services where needed. Record facts and retain relevant documents. Consult the existing policy's procedure and deadlines. Do not copy a deadline published for another product or later modify evidence to support a particular explanation.
Clarify claim management, lawyer involvement and communication with the affected person. A commercial agreement or voluntary payment should not be assumed automatically reimbursable. The broker can help organise information; the insurer assesses the loss within the applicable documents.
Frequently asked questions about third-party liability
Does company property insurance include a neighbour's loss?
Do not assume equivalence. Your own property and liability for someone else's loss must be distinguished and checked in the relevant documents.
Is every item received from a customer protected?
Request an assessment of entrusted property and the operation performed. Its presence on the premises does not itself confirm policy inclusion.
Is work at a customer's site included automatically?
Check the accepted activity, territory and locations. Describe actual operations, including installation and maintenance.
Who decides whether an incident is compensated?
The insurer handles the case under the contract and applicable framework. The broker should not be presented as the payer of compensation or a guarantor of the outcome.
Next step
Request a discussion with ING Broker to check assessment and brokering possibilities. The broker explains options and acts as intermediary. Risk acceptance, conditions and claims decisions belong to the insurer under the contract. This guide does not confirm product availability or cover for an individual case.
Read also: Professional liability for services provided.
Sources and information limits
The Romanian original records consultation of these sources on 8 November 2026. The translation revision date does not represent a new legal or product verification. Preparation lists are editorial recommendations, not policy conditions. Product examples from cited providers do not constitute an ING Broker offer. Legal obligations and individual circumstances require specialist review.