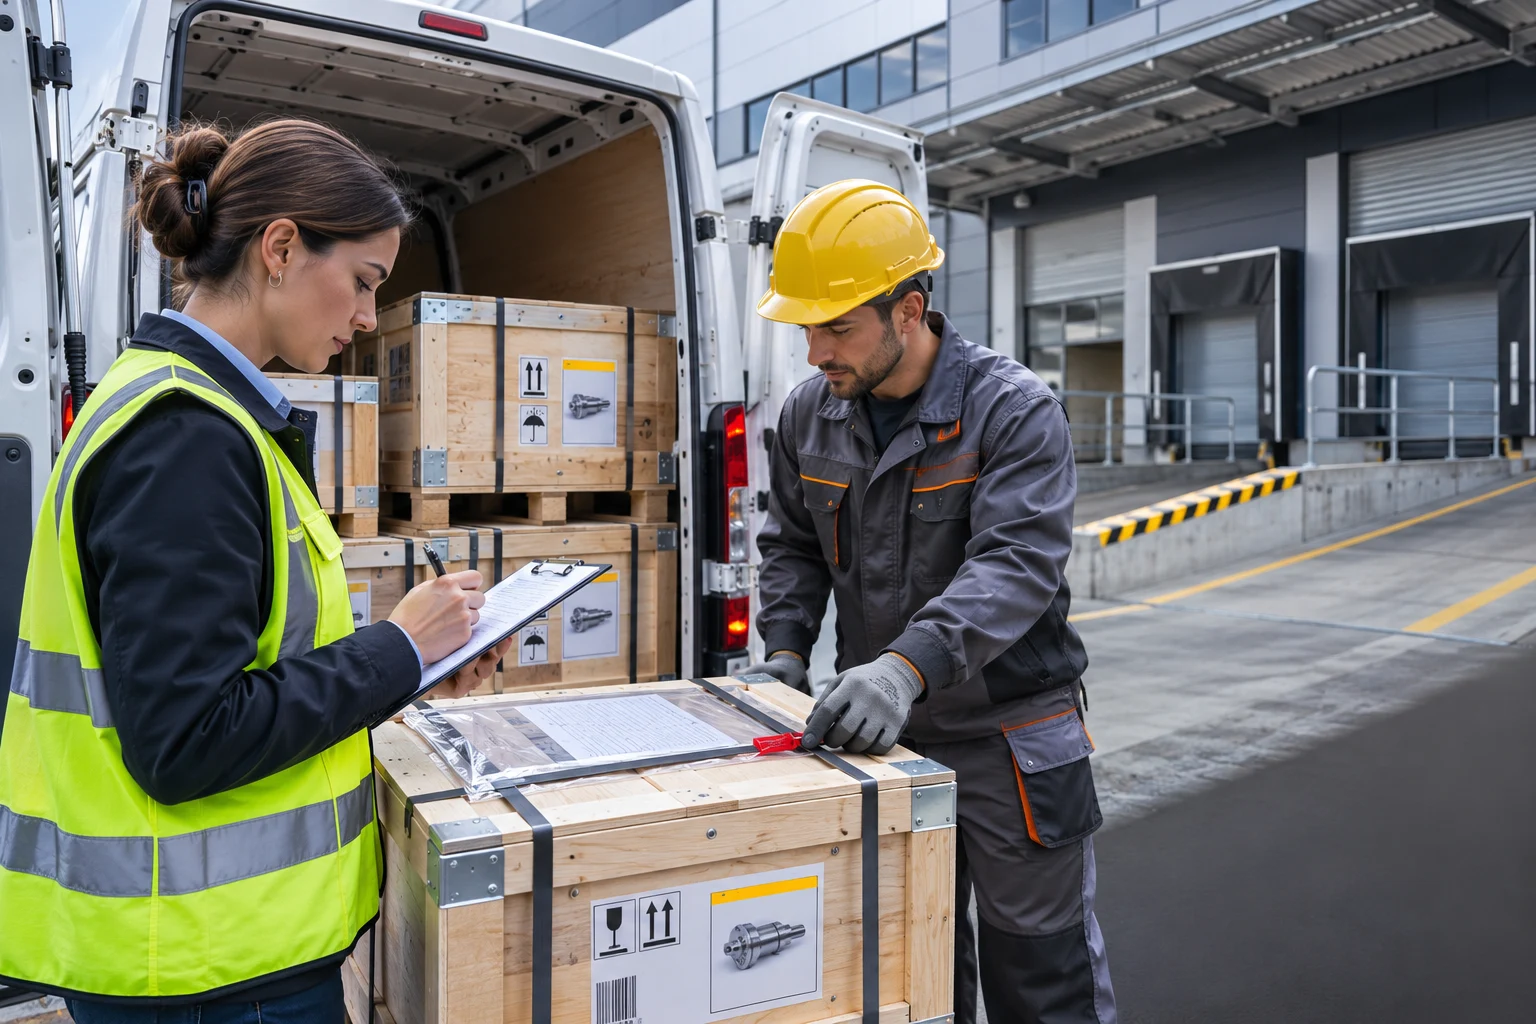

Goods in transit: preparing insurance for a delivery
Goods in transit insurance concerns cargo during a delivery under conditions accepted by the insurer. For a Moldovan company, assessment starts with the goods, value, route and stages. Knowing that a carrier has insurance is insufficient: distinguish documents protecting the goods from those concerning carrier liability.
This article follows preparation for an actual delivery. For the product overview, see the CARGO article. Here importers, exporters, distributors and manufacturers can organise information before departure, changes on route and records at receipt. It does not confirm cover for every commodity or destination.
Who has an interest in the goods at each stage?
Identify seller, buyer and transport organiser. Explain ownership and commercial responsibilities. Ask about unfamiliar delivery terms using the actual wording and documents. Do not infer who bears a loss solely from one company having paid for the truck. The commercial agreement and the actual handover arrangements need to be understood together.
Prepare the relevant order or contract and handover points. For several carriers, describe their sequence: who hands over, who receives and which document records it? The broker can prepare insurance assessment; commercial duties in a dispute require contract review and, where appropriate, legal support.
Describe the goods so they cannot be confused with another lot
Replace general cargo with useful details: goods, quantity, packages and packaging. Explain finished goods, components, raw materials or used property. For equipment, identify principal elements and references. Do not publish sensitive serial numbers or commercial documents in a contact form; agree their transmission separately.
Describe route-sensitive characteristics. Glass, fruit and machinery require different explanations. Record fragility, sensitivity to moisture, required storage conditions and the supplier's handling instructions. These characteristics explain why a lot of glass, a shipment of fruit and an industrial machine should not be described in the same way. This does not mean every risk is included; it allows appropriate questions before choosing a proposal.
Documenting the value of transported goods
Prepare an invoice, purchase record or other support for declared value. Separate currency, goods value and other expenses to discuss. Ask which valuation basis the proposal accepts. Do not automatically add a profit percentage or extra costs copied from an online example.
Check invoice descriptions against the packing list and insurance application. For several invoices in one truck, link documents to packages and recipients. If values change before departure, update the file and ask for the consequences to be checked against the revised request. An earlier calculation does not automatically protect quantities or values added later.
The route is more than departure and arrival cities
Record countries, vehicle changes and transport modes. Explain direct delivery or distribution-centre handling. For truck, rail and sea combinations, show every known leg. Do not present an approximate route as confirmed when an operator will choose it later.
Discuss diversions, destination changes and unplanned stops separately. Who reports changes, to whom, and is written confirmation available? Read territory with the conditions rather than a short marketing phrase. For a territory or situation that remains unclear, leave the question explicitly open until the insurer responds. Neither a route estimate nor an unanswered request should be recorded as a confirmed condition.
Assess loading, unloading and stops separately
Map packing, loading, transport, intermediate storage and unloading. For each operation, record the party performing it and the equipment used, including responsibility for intermediate handling. Damage may be noticed at destination without its timing immediately known. Consistent stage records describe facts but do not independently establish cause or responsibility.
Ask exactly when protection starts and ends and how each stage is treated. Warehouse property insurance does not establish transport inclusion; CARGO does not confirm every stop or storage period. Check actual wording, time and location limits rather than substituting this article for conditions.
Packaging and securing information
Keep packaging specifications and handling instructions. Describe pallets, crates, protection and identification. If the lot will be repacked during the journey, describe that operation and identify the responsible party. Keep it distinct from the initial packing arrangements at the point of dispatch. Safely taken photographs can support records but do not replace documents or certify technical packaging suitability.
Do not improvise securing work to obtain a marketing photograph. Use competent people and transport procedures. Record pre-existing damage honestly and request assessment. A new policy must not be presented as solving a loss already observed. Acceptance must use actual information, not idealised descriptions.
Temperature-controlled goods raise additional questions
For sensitive products, prepare supplier-specified storage ranges and equipment details. Identify monitoring responsibility and available records. Distinguish compartment air temperature from other product-relevant measurements. Technical, sanitary and food-safety requirements must be checked by competent specialists and documents.
Ask separately about refrigeration breakdown, power interruption, delay and temperature deviation. Do not combine them into one assumed accepted risk. Distinguish technical information, contractual conditions and observations. An app screenshot alone does not establish duration, cause or extent of cargo loss.
Single delivery or repeated shipments?
Prepare individual lot details for one trip. For regular deliveries, show frequency, usual routes, changing values and categories. INTACT publicly presents Moldovan goods-in-transit insurance for individual shipments and lots over a period. This is a local example, not identical availability for every business.
For a programme, clarify declarations, documents and limits. Who sends information and how is receipt confirmed? A new shipment is not automatically included merely because the company already has a policy. Ask for a process explanation using your business without editorially invented values or deadlines.
CARGO and CMR do not answer the same question automatically
CARGO concerns goods under its insurance conditions. Carrier liability concerns the carrier's responsibility under its own terms. For the actual delivery, read separate documents and identify parties. A carrier's policy is not a promise of full owner recovery.
Having both documents does not permit automatic addition of amounts or assumed double payment. Retain chronology, records and communication after a problem. Responsibility, contractual application and compensation assessment belong to competent parties and the insurer as applicable. The broker does not replace the insurer's claims decision.
Receipt: record observations without premature conclusions
Assign a recipient and checks of package numbers and visible condition. Retain handover documents and actual observations. Follow agreed procedures for discrepancies. Do not certify problem-free receipt merely to hurry unloading or alter documents later to reconstruct unrecorded circumstances.
Put personal safety first and use competent services where necessary. Notify the insurer under the contract and request evidence-preservation and assessment instructions. Do not publish people, identity numbers or commercial data. Do not independently decide destruction, repair or sale before necessary checks.
A delivery sheet you can prepare now
- Goods, quantity, packaging and lot identification.
- Value documents and currency.
- Commercial parties and company coordinator.
- Route, carriers and intermediate stages.
- Loading, unloading and stopping periods.
- Special storage conditions and documents.
- Limits, exclusions and deductible questions.
- Responsibility for changes and receipt.
Use the same sheet for proposals. The premium is the amount paid, the deductible is the insured's own share under the contract, and exclusions are uncovered situations. Fill answers from documents, not assumptions. Initially describe the delivery to ING Broker without sending sensitive files through a public form.
Illustrative delivery version-control check
A distributor adds two crates, and logistics updates the packing list, but the assessment sheet retains the initial quantity. This is hypothetical, not a real client. Before departure, compare both documents and request review of updated information. An update alone does not establish acceptance of extra value.
Assign someone to obtain confirmation and final documents. The driver's copy is not the preliminary calculation draft. Matching package identifiers at receipt connects observations to the dispatched lot. Coherent records do not replace damage assessment, responsibility review or policy conditions.
Frequently asked questions about goods in transit
Can I request assessment after the truck leaves?
Disclose the actual departure date and circumstances. Do not assume protection can begin retrospectively or that a known loss can be included. Availability and the commencement of protection must be confirmed before the transport is treated as insured.
Does a public rate apply to every commodity?
Do not use a public example as a personalised offer. The type of goods, their value, the route, transport stages and requested conditions need assessment. Compare the price together with the limits and exclusions in the actual proposal.
Can shop property insurance protect customer deliveries?
Do not infer this from the goods having the same owner. Check the subject, locations and operations specified in the contract. Transport to a customer and storage at the business premises are separate questions that need clarification.
What if the route changes?
Report the change through the agreed channel and ask for the conditions to be checked before assuming they remain unchanged. Keep the relevant confirmation and update the delivery sheet, including additional operators or stops.
Next step
Request a discussion with ING Broker to check assessment and intermediation possibilities. The broker explains options; acceptance, conditions and claims decisions belong to the insurer under the contract. This article does not confirm availability or individual cover.
Read also: CARGO insurance: goods and conditions to check.
Sources and limits of this information
The Romanian source consulted these sources on 11 November 2026. Lists are editorial recommendations, not policy conditions. Examples are not an ING Broker offer. Legal obligations and individual situations require specialist verification.