
Logistics warehouse insurance in Moldova
Warehouse insurance is not limited to the building. Assessment may separately address premises, installations, equipment, the business's stock and goods held for customers, to the extent accepted under the contract. For a Moldovan operator, a useful first step is an inventory showing each category's owner and location.
This article is for warehouse managers, distributors, importers and businesses renting storage space. It does not confirm a policy valid for every item or incident. Its purpose is to prepare the site file and distinguish proposals without confusing property protection with operator liability or transport insurance.
Building owner and warehouse operator may differ
Start with the agreement under which the company uses the premises. Record whether it is owner, tenant or manager for another company. Distinguish the building, tenant-funded improvements and the owner's assets. If several companies occupy one warehouse, describe their areas and activities rather than only the shared address.
Request a written explanation of people and interests that may be included. Do not assume the owner's insurance protects the tenant's stock or that an operator's policy replaces every lease obligation. Legal interpretation of those obligations is separate from comparing insurance proposals.
Separate inventories for building, installations and improvements
Prepare floor area, use of spaces, principal materials and actual operations. Include loading areas, annexes and relevant technical rooms. For installations, state ownership and maintenance responsibilities. The words storage building do not explain a cold room, workshop or packing area.
Check whether outside property, platforms and auxiliary structures appear in the documents. Ask where building components end and mobile equipment begins. A global property sum does not automatically include every later investment. Update the inventory after expansion and seek confirmation before assuming protection has expanded.
Describe stock changes and seasonal peaks
A warehouse may hold little stock one day and much more before a sales season. Prepare available monthly history, maximum values and goods categories. Explain valuation methods and supporting records. A photograph of a half-empty warehouse does not replace accounting and operational evidence.
Ask how stock variations must be declared under the proposed arrangement. Request explanations of the sum insured, category limits and circumstances requiring notification. Do not automatically use an average if substantial seasonal concentration is possible. The accepted basis belongs in the documents.
Customers' goods are not automatically company property
When holding goods for other businesses, identify ownership and the basis of receipt. Record batches and entry and exit times. For an initial discussion, do not send full confidential customer lists if aggregated categories and values suffice. First agree required information and a suitable channel.
Distinguish insuring goods from the operator's liability for harm. Loss of customer property and a claim against its custodian cannot be assessed merely by changing a policy title. Present relevant contracts and ask for the proposed boundaries without promising partners that every event is covered.
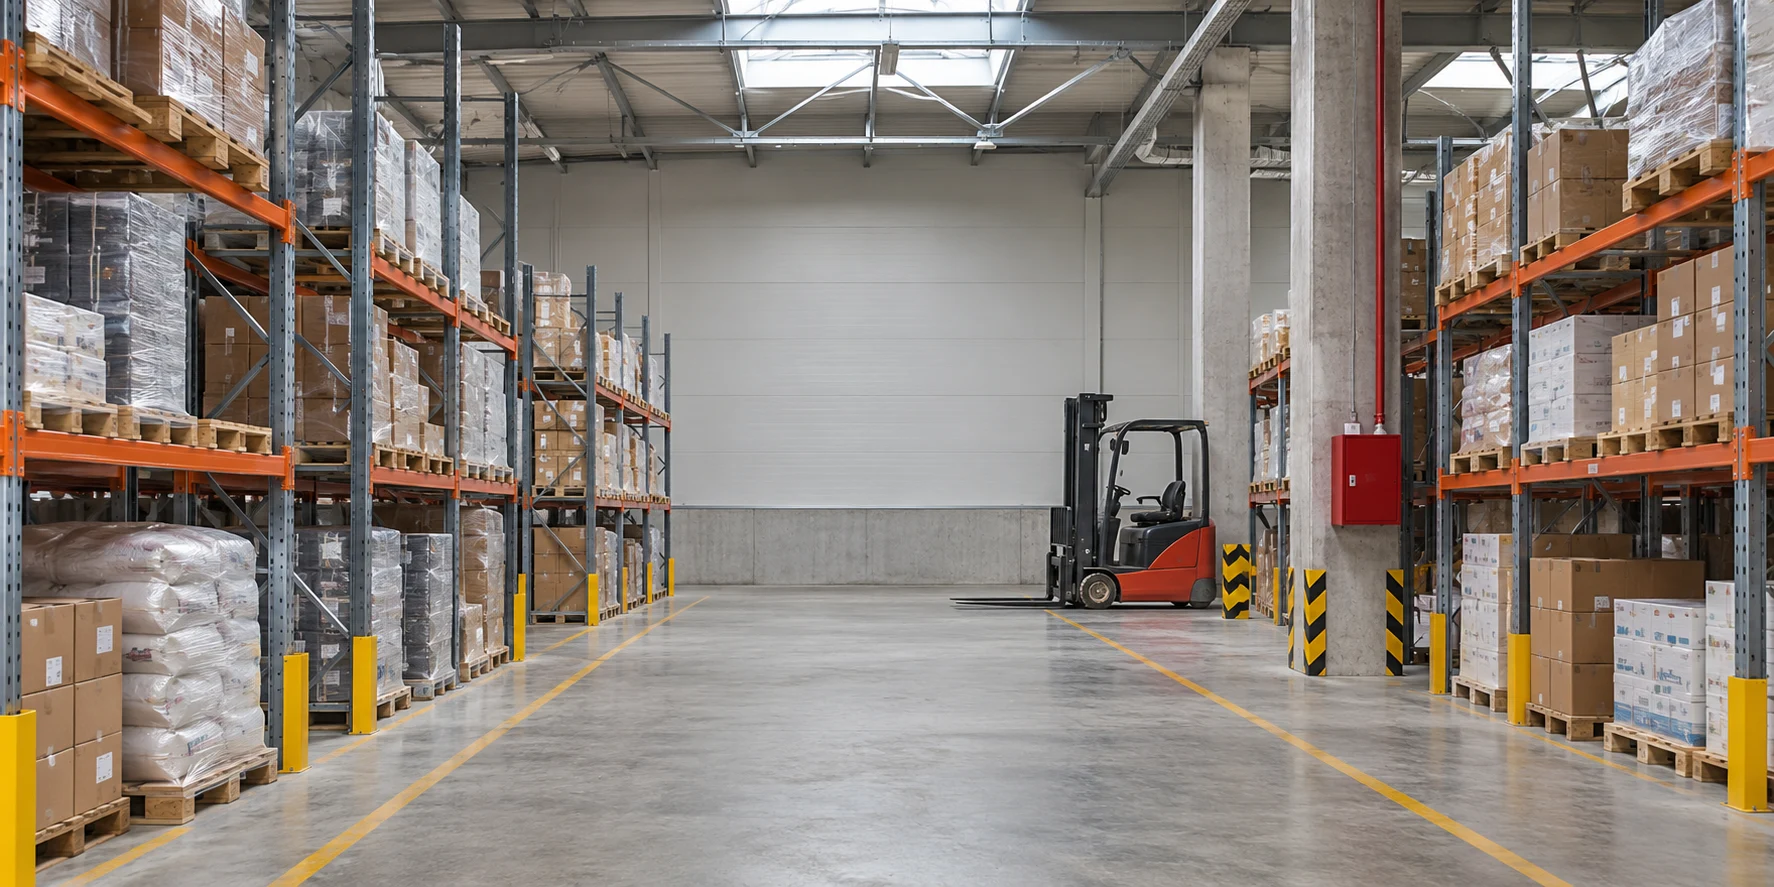
Match each operating zone to its purpose, property owner and valuation records. Keep ordinary storage separate from packing or special-temperature areas. This is an organizational example, not a safety assessment or confirmation of cover. Where customer goods are present, record the basis of custody without unnecessarily circulating confidential customer lists.
Describe actual warehouse operations
Explain receiving, sorting, repacking, labelling, storage and dispatch where applicable. State whether goods undergo technical work or are simply stored. Include forklifts, conveyors and loading ramps. Warehouses of equal floor area may present different exposures because their operations differ.
Include subcontracted activities. For maintenance, temporary work or intervention on installations, ask what must be disclosed and which conditions apply. A secondary activity is not automatically included merely because it takes place on site. Describe operations capable of influencing assessment.
Document fire prevention and security
Prepare information about detection, alarms, access and installation maintenance. Describe existing conditions and outstanding repairs. A system on an old plan is not proof it currently works. Distinguish equipment installed, equipment checked and equipment actually used under an internal procedure.
Document storage arrangements and access to circulation routes. This editorial list is not a fire-safety audit or compliance certificate. Legal requirements need separate checks with competent specialists. Request the proposal's actual requirements and consequences of non-compliance in writing.
Cold rooms and sensitive goods
For goods requiring controlled temperature or humidity, describe operating ranges, monitoring, electricity supply and backup arrangements. Separate equipment damage, spoiled goods and moving stock elsewhere. A building policy does not automatically establish acceptance of all these consequences.
Ask explicitly about equipment stoppage, supply interruption and accepted storage periods instead of assuming answers. Keep maintenance and storage-condition records. Identify goods with special requirements separately from ordinary stock. Do not hide them within a general warehouse category.
Storage is not the same as CARGO transport
Explain when goods arrive, how long they remain and when they are handed to a carrier. Distinguish normal storage from a temporary stop during a shipment. For CARGO, read the actual stages and periods in its conditions. A transport label does not confirm unlimited storage.
Create a simple batch timeline: receipt, inspection, storage, preparation, loading and departure. Identify evidence for each transfer and who keeps it. This organization helps assessment but does not itself determine liability or an insurer's payment obligation.
What if the warehouse cannot operate?
Identify activity needing relocation and the resources required. Is alternative space available, with equipment and suitable storage conditions? Distinguish estimated costs from amounts supported by quotations. A continuity plan is an organizational measure, not a compensation calculation.
For business interruption, ask about the triggering event, period and expenses considered. Repairing the building and restoring normal logistics are not identical. Late deliveries, customer penalties and lost orders need separate discussion, not presentation as implicitly included benefits.
Prepare the same file for each comparison
- Address, purpose and functional site layout.
- Company role: owner, tenant or operator for others.
- Buildings, installations and equipment inventory.
- Stock categories, substantiated values and seasonality.
- Own goods separated from goods held in custody.
- Operations and special storage conditions.
- Prevention systems, maintenance and relevant incident history.
- Separate questions on transport, liability and continuity.
Use the same file version for every proposal. Mark estimates and outstanding documents. Ask which categories are not accepted or need additional conditions. Do not compare the premium, meaning the amount paid for insurance, without checking which property and situations were actually assessed.
Use the same site description for each proposal and identify the version to which an answer relates. A blank answer about seasonal stock or a cold room is not equivalent to an expressly confirmed section. Keep that issue open and request clarification. When premises expand, preserve both the previous description and the changes so the discussion concerns the actual site rather than an outdated questionnaire.
Expansion and changes during the year
A new tenant, additional storage area or new packing operation can change the site's description. Record the date and extent of the change, then ask which documents are needed. Do not wait until renewal to discuss circumstances absent from the initial file.
Separate planned work, ongoing work and already occupied space. A proposal for an operating building does not confirm every expansion-work risk. Explain contractors' roles and request separate assessment of insurance requirements without assuming policies replace one another.
Organizing an incident file
Prepare an internal procedure for preserving facts and contacting responsible people. After an incident, follow applicable instructions and do not compromise safety for photographs. Batch records, receipts, findings and valuation evidence may help, but the actual document list is determined for the individual case.
Distinguish company and customer goods, their location and the period covered by records. Do not announce compensation before assessment or alter documents to fit an inaccurate first description. Insurance ING Broker SRL is a broker; the contractual claims decision belongs to the insurer.
When a stock figure includes both owned goods and items held for customers, retain the ownership breakdown and the supporting custody records. The combined total cannot identify which interest a proposal has actually assessed.
Frequently asked questions
Does the building owner's policy protect my goods?
Do not assume it. Request the applicable documents and check the subject, protected persons and interest in your company's stock.
How do I choose a sum for changing stock?
Prepare historical and peak stock values, then ask about the accepted declaration format and valuation basis.
Is cold storage assessed like an ordinary warehouse?
Do not treat them as identical. Describe installations, goods requirements and electricity dependence, then check each requested consequence separately.
Does building insurance include interruption?
Not automatically. Request a separate review of losses and proposed conditions using records of actual warehouse operations.
Next step
Request a conversation with ING Broker to check assessment and intermediation possibilities. The broker explains options and arranges insurance. Risk acceptance, conditions and claims handling belong to the insurer under the contract. This article does not confirm product availability or coverage of an individual case.
Related reading: Goods insurance during transport.
Sources and limits
- National Bank of Moldova: reading an insurance contract
- MOLDASIG: property insurance for legal entities
The Romanian original records source consultation on 8 November 2026. The translation revision date does not mean the sources have been checked again. Preparation lists are editorial recommendations, not policy conditions. Cited products belong to their providers and are not ING Broker offers. Legal obligations and individual circumstances require specialist verification.